

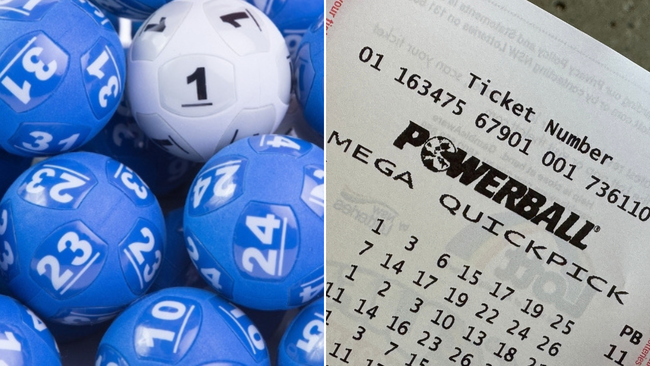
As Australians rush to secure tickets for Thursday night’s $100 million Powerball draw, financial experts are warning that winning the jackpot is only half the battle.
The other challenge is making sure the money lasts.
Senior financial adviser Simon Robinson from accounting giant RSM Australia says a lottery win can be life-changing, but without a plan, even a vast fortune can disappear quickly.
Know the news with the 7NEWS app: Download today
“A lotto win isn’t necessarily a ticket to financial freedom,” Robinson said.
“The statistics around people losing all their winnings and/or going bankrupt are stark.”
Robinson pointed to research suggesting many lottery winners burn through their fortunes within years, highlighting the importance of careful planning from day one.
For anyone lucky enough to wake up $100 million richer on Friday morning, his first piece of advice was simple: keep it quiet.
“Keeping news of your win to a small inner circle of trust is critical until you have a plan and have suitably structured your newfound wealth to support that plan,” he said.
“There might be a list of people you desperately want to share this wealth with, but there is likely a much longer list of people who will want you to share your wealth with them once they know you have $100m in the bank.”

Robinson said friends and family can unintentionally become one of the biggest pressures on lottery winners.
“Unfortunately, friends and family can become the biggest threat as you may feel guilty or obliged to help them,” he said.
“Some might demand it, others may simply expect that you’ll pick up the bill next time you go out for dinner.”
Before making any major purchases, Robinson recommends taking time to think through exactly what winning means and what goals the money should achieve.
Whether it’s paying off a mortgage, helping children buy homes, travelling the world, buying a luxury car or supporting charities, any ambitions should become the foundation of a long-term financial structure.
“Don’t commit to anything until you have a plan,” he said.
While it may be tempting to start spending immediately, Robinson recommends parking winnings in a high-interest savings account while decisions are made.
“Imagine the horror of having your debit card skimmed and losing a big chunk of that wealth,” he said.
“It might also help stop the impulse spend while you get your plan in place.”
Professional advice is another must, according to Robinson, who said winners should consider assembling a team including an accountant, lawyer and qualified financial adviser.
“There are various tax structures that might work for you, and getting this right up front can help avoid big problems down the track,” he said.
Robinson also urged winners to carefully consider risk, investment returns and access to cash before deciding where to put their money.
“Liquidity is also going to be critical as earnings on your winnings are likely to attract a much bigger tax bill than your last income tax return,” he said.
Asset protection should also form part of any strategy, particularly when it comes to safeguarding wealth from future disputes, creditors or relationship breakdowns.
“Family trusts and companies may also be useful depending on your circumstances,” Robinson said.
For hopeful punters dreaming of Thursday night’s draw, Robinson said the key message was that winning the money is only the beginning.
“Winning is only the first step, and planning for how to make that win give you financial freedom is the next and most critical step,” he said.